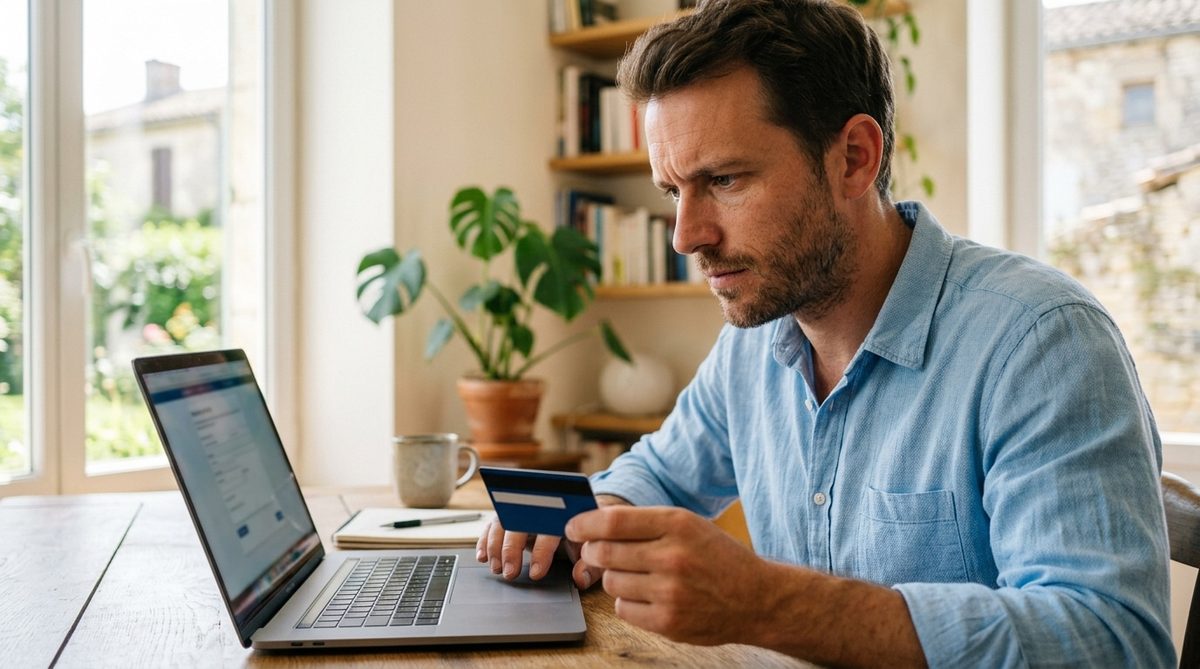
Summer is basically a fun time. Air conditioning, backyard, school supplies. But there’s one small detail about your debit or credit card that can cause real panic. Its expiration date.
It is printed on the front. month and year. This indicates that the financial instrument is approaching the end of its useful life.
Most people think that cards are valid for five years. The legal maximum is around this mark. Most banks prefer a three-year period. Why? availability. The chips wear out. Security protocols are constantly evolving. New cards mean new encryption. You’re also no longer stuck at the checkout because of a rejected transaction abroad.
Understanding this mechanism requires more than just paperwork. This will avoid the sweaty moment when your device beeps with rejection.
The exact moment when the card stopped working
The lifetime of the readings follows strict chronological rules. It is often misunderstood.
If your card says July 2024, then yes. All through July. You can swipe, tap, or dip until the clock strikes midnight on July 31st.
The deadline is August 1 at 12:00.
immediately. The interbank network prevents authentication. There is no grace period. Just as you can’t wait until the first frost to protect your garden, you should pay attention to this date.
Current devices do not recognize chips or magnetic stripes at all. This is not a fault. This is a safety measure. Banks are forced to make this transition to maintain up-to-date anti-piracy and anti-fraud measures. Summer is the peak season for theft. They tighten the screws.
Why your account is safe even when your card expires
If you are even a minute late for the monthly deadline, rejections will occur systematically.
**Expired cards may be declined and must be renewed or exchanged to continue payment. **
Can I withdraw money from an ATM? No, Physical transactions at hardware stores? Impossible. Plastic rectangles are not suitable.
But don’t worry. your money is safe. The bank account itself remains active. The funds are secure. Only access tools are broken.
The real pain is the recurring fees associated with these 16 card numbers.
Phone subscriptions. Streaming services. Regular grocery delivery. All such automatic withdrawals will be rejected. The services related to them will be stopped immediately. If you forget to check the date on the card in your wallet, you may forget to pay your bill or miss out on services.
Here’s a breakdown of what happens expiration hits:
General banking services
Status after expiration
Contactless payment at a merchant
Completely blocked
withdraw cash from an ATM
impossible
An invoice related to the card number
Systematically rejected
Use an IBAN account for SEPA money transfers and direct debits
Remains functional
Pay attention to the last point. Your IBAN number is linked to your account, not your card. Direct debits and bank transfers are still available. Card-specific authorizations are gone.
How to change payment method instantly
The financial system is designed to make life easier. Renewal is mostly automatic.
Your new card will arrive about a month before your old card expires, unless you have specifically opt out with your bank advisor.
Most banks will send this to your mailbox by the 15th of the final month. Simple mail. or by registered letter.
For your safety during your vacation, your replacement card will be locked upon your arrival. Disabled.
Usually the PIN remains the same. Or it may arrive in a separate envelope a few days later. This split delivery protects your data.
There will be delays in the post office. Especially in summer. If you haven’t received your letter, there is a solution.
Create a virtual card.
Use your banking app. A unique number is generated. Use it for urgent online purchases. It buys you time. You can still make payments until you receive your physical card.
This is a small digital bandage. But you might end up waiting in line at the store with your card in hand and staring at a screen that says “Reject.”
Check your wallet. See the date. If it is close, order the renewal. Or enable the virtual option. Don’t wait for the beep.
Why you need strategic disposal for expiring cards
You don’t need a degree in finance to manage the lifecycle of a payment card. Treat it like any other household item nearing its expiration date. If you skip this process, you risk having your service shut down suddenly when you really need to spend money. The transition from an outdated card to a new one should be smooth. Vigilance is required.
Start early. Most banks will send you a notice about 30-45 days before the due date. But waiting for that email was a gamble. Check your mailbox (digital and physical) two months before the date printed on the card. If you skip this window, your transaction may be rejected at checkout.
When you get your new card, don’t just hide it in a box. Activate now. Use a primary ATM. Insert the chip. Enter your PIN code. Make sure the balance is right. This step ensures that the chip is valid and that your bank has linked your new card to your existing account. It also helps to practice safety measures before stress.
This is the hard part. Dispose of your old card properly. Scissors are usually sufficient, but be sure to do it carefully. Cut the magnetic strips. Cut off the chips. Cut the card number. It’s not just about tearing it in half. If you have a paper shredder, cut it into small pieces. Garbage disposal units may be able to reconstruct enough data for fraudsters to attempt manipulation or identity theft.
“Destroying the old card is not only about protecting your privacy, but also preventing it from being accidentally reused on a device whose database hasn’t been updated.”
Update recurring payments. This is where most people fail. Netflix, Spotify, gym memberships, utilities. These services are billed automatically. If the card number changes (which it almost always does), the card fails. The service has been stopped. Late fees will be charged. You will be locked out. Go through your subscriptions list now. Update your card information on each platform. Do it in one sitting.
This proactive approach preserves purchasing power. Avoid late fees. This can prevent service interruptions. The cost of updating your information for 10 minutes is zero. The cost of declining a payment or locking your account is time, stress and possible penalties.
What are your plans for summer vacation? Are you paying your bills? Can you move forward without any problems? It all depends on this administrative chore. You don’t have to wait for your card to be declined when you’re in line at the checkout and the line behind you gets longer.